How final expense insurance works in Canada: Costs, eligibility, and timelines
The CPP death benefit is usually a one-time $2,500 and most funerals in Canada cost far more. How final expense insurance covers the gap and what it costs.
On this page
- Key Takeaways
- What is final expense insurance?
- How to check that a final expense insurer is legitimate
- How does final expense life insurance work?
- Benefits of final expense insurance
- Types of final expense insurance
- How does graded death benefit work?
- Real-life examples
- Final expense insurance vs. Term Vs. Permanent life insurance policy
- Who needs final expense insurance?
- Does the government help you pay for a funeral?
- How much does a funeral cost in Canada by province?
- Policy expiration and renewal
- How final expense insurance works in Canada – Conclusion
- Frequently asked questions about final expense insurance Canada
Is final expense insurance in Canada legit? Yes. It is a real, regulated product: life insurance sized to cover the funeral and final bills, paid to your family as a tax-free lump sum. Every seller must be licensed in your province, so check the licence, ask who underwrites the policy and read the waiting-period terms before you pay.
Planning for the end of life is never easy, but ensuring your family isn’t left with unexpected bills is one of the most thoughtful steps you can take. Final expense insurance, sometimes called burial insurance, helps cover funeral, cremation, and related costs so loved ones aren’t financially burdened. Planning for funeral arrangements is an important part of preparing for final expenses, as these costs can add up quickly and potentially cause financial stress for loved ones after one’s passing.
Government help is limited. The CPP death benefit is a one-time $2,500 payment (a top-up to $5,000 exists, but only where no CPP pension was ever paid and no survivor's pension is payable). That top-up is new for deaths on or after January 1, 2025. Either amount rarely covers a full funeral, which is the gap final expense coverage is meant to fill.
Designed for simplicity, these policies often require no medical exam, and guaranteed-acceptance versions accept every applicant in their age range, usually with a waiting period. Oneday offers coverage to residents of Ontario, British Columbia, Alberta, Manitoba, Saskatchewan, New Brunswick and Nova Scotia.
In this guide, we’ll outline how final expense insurance works in Canada, who it’s for, and how to choose coverage that fits your legacy goals. Planning for final expenses is as important as other life planning efforts like saving for retirement.
What is final expense insurance?
Final expense insurance is a type of life insurance product specifically designed to cover immediate expenses when the insured person passes away. Final expenses insurance provides a lump sum cash payout to beneficiaries, which can be used promptly for funeral costs, unpaid bills, credit card debt, or other expenses. Our guide to funeral costs in Canada has real prices by province.
The coverage amount provided by a final expense insurance policy is generally lower and can differ based on the policy and the insurance provider. However, in general, final expenses insurance cover typically includes the following: In Canada, the cost of a funeral can range from a modest $5,000 to well over $15,000.
- Funeral costs: Embalming, casket or urn, viewing or visitation, transportation of the body, and the funeral ceremony itself.
- Burial or cremation costs: Burial plot, a headstone or grave marker, burial vault, the services of a gravedigger, and cremation costs, including the cremation process, urn, and associated fees.
- Outstanding debts: Medical bills, credit card debt, unpaid bills, or personal loans left behind by the deceased.
- Final expenses insurance cover: Specifically provides for funeral and memorial expenses, and helps alleviate financial stress for beneficiaries by covering end-of-life costs, including unpaid bills and credit card debt.
Final expense insurance policies typically offer lower coverage amounts from a few thousand dollars to around $25,000. However, some insurance providers may offer higher coverage limits, reaching $50,000 or more. The maximum coverage will depend on the specific policy and the insurance company’s offerings. The cost of final expense insurance depends on personal factors such as age, gender, and health status.
Some life insurance companies may have different age ranges, such as starting coverage at age 55 or extending coverage beyond age 85 to be eligible for final expense insurance.
How to check that a final expense insurer is legitimate
Final expense coverage is sold hard on TV, online and over the phone, so it is fair to ask whether an offer is real before you pay. You can check almost all of it yourself, for free, in an afternoon. These are the checks we would want you to run on anyone, including us.
- Confirm the seller is licensed in your province. Agents must be licensed in the province where they do business, and the Financial Consumer Agency of Canada says to confirm that before dealing with them. Look up the agent and the company named on your quote: Ontario (FSRA), British Columbia (Insurance Council of BC), Alberta (Alberta Insurance Council), Manitoba (Insurance Council of Manitoba), Saskatchewan (Insurance Councils of Saskatchewan), New Brunswick (FCNB) and Nova Scotia (Superintendent of Insurance). If you can't find them, don't buy.
- Find out who underwrites the policy. The company in the ad is not always the insurer that pays the claim. Ask for the insurer's full legal name, make sure it appears in your policy documents, and check it against the Assuris list of member companies. Every life insurer authorized to sell insurance in Canada must be a member, and Assuris protects policyholders if a member insurer fails.
- Read the waiting-period terms. Many final expense policies, especially guaranteed-acceptance ones, pay back premiums or only part of the benefit if a death from natural causes comes in the first two or three years. Ask what is paid in each year and whether accidental death is covered in full from day one, and get the answer in writing. Ours is explained in what a 24-month deferral means.
- Use the free-look period. You can cancel a new life insurance policy within a set period, usually 10 days, and get your premiums back. The life insurance industry's own guideline G10 calls for a 10-day free look. Oneday's free look is 30 days. Read the policy as soon as it arrives.
- Never pay in cash or gift cards. Pay the insurer directly, by pre-authorized debit, credit card or a cheque made out to the insurance company, and get a policy number and written confirmation. New Brunswick's regulator is blunt about it: no company will ask you to pay with a gift card. If anyone does, hang up and report it to the Canadian Anti-Fraud Centre.
- Walk away from pressure. A price that "ends tonight", a caller who won't let you hang up and call back, or coverage tied to something else you want are warning signs. Ontario's regulator has warned about fake job offers that required people to buy life insurance first. A real offer will still be there after you check a licence and sleep on it.
If something still feels wrong, call your provincial regulator before you sign anything. If you already have a policy and a dispute with the insurer, the OmbudService for Life and Health Insurance offers a free and impartial review of complaints.
How does final expense life insurance work?
Final expense insurance works similarly to other types of life insurance. The policyholder pays regular monthly or annual premiums to keep the policy in force. The policy provides a guaranteed death benefit, which is paid to beneficiaries if the policyholder passes away while the policy is active.
The insurance company pays out a death benefit to the designated beneficiaries upon the policyholder’s death. The life insurance death benefit can cover final expenses, such as funeral costs, burial or cremation expenses, memorial services, and related fees. The funds can also be used to help replace lost income for beneficiaries or for other purposes, depending on the policy terms and the beneficiaries’ discretion.
Policyholders can also use life insurance to go directly to the funeral home. This type of insurance is known as pre-need insurance and is commonly provided by funeral homes in collaboration with insurance companies. It involves making premium payments over a specified duration, and upon the policyholder’s demise, the insurance company disburses the death benefit directly to the funeral home.
Opting for final expense insurance is often preferable to pre-need insurance. Final expense insurance provides greater flexibility as beneficiaries can use the death benefit for various expenses, not limited to final expenses, thus allowing them to control how the funds are used. While final expense insurance is primarily designed to cover immediate costs, it can also provide financial support to replace lost income for a short period.
Benefits of final expense insurance
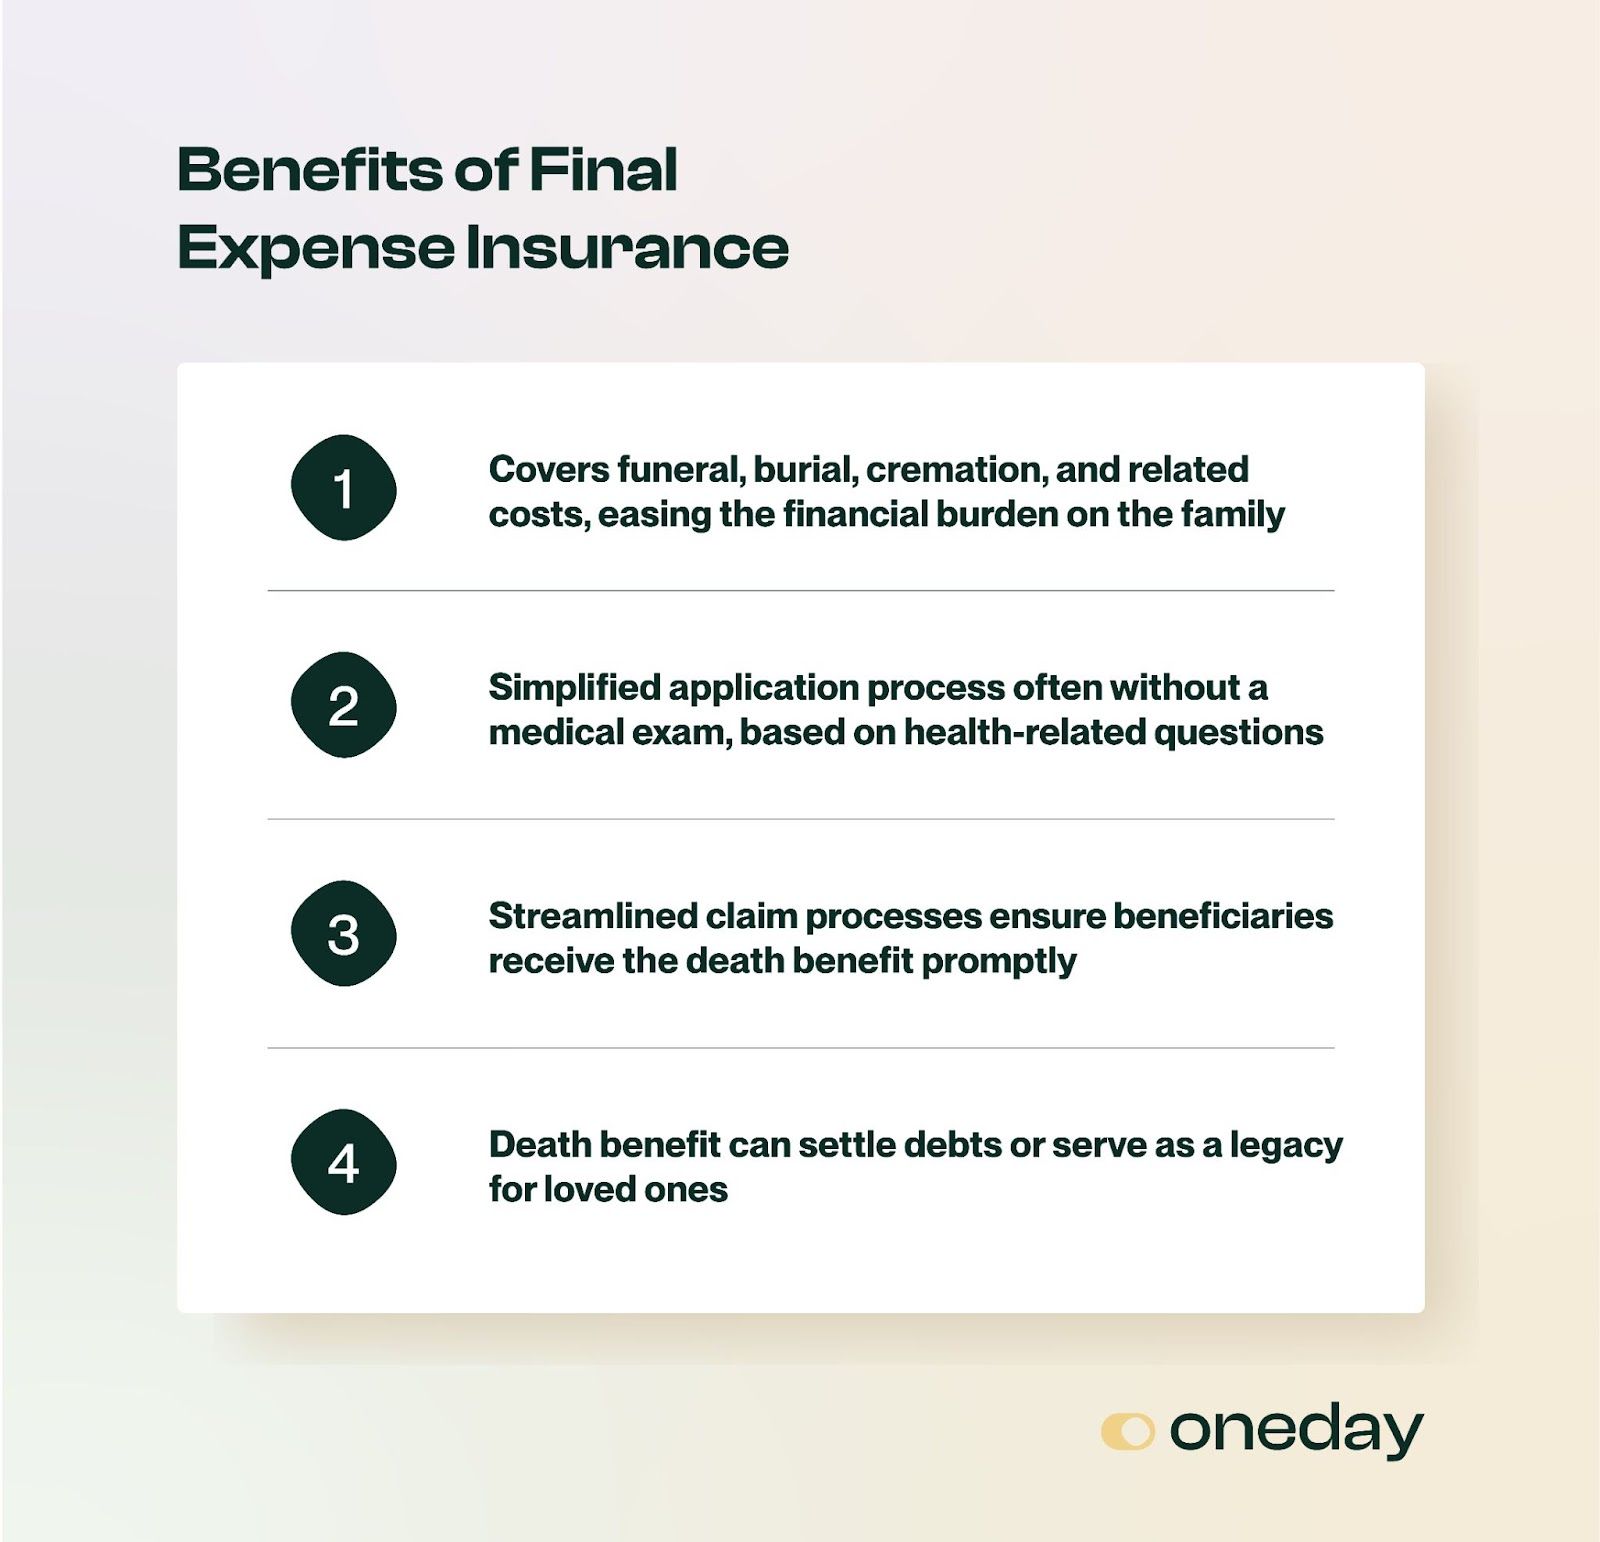
- Provides life insurance coverage specifically tailored for end-of-life expenses, including final expenses, burial, cremation, and related costs, ensuring that the financial burden of these expenses does not fall entirely on the individual’s family members or loved ones.
- The application process typically requires sharing health-related information and may not need a medical exam.
- Final expense insurance policies generally have a streamlined claims process.
- Final expense insurance can also assist in covering estate taxes, ensuring a comprehensive financial strategy for end-of-life expenses.
- The death benefit offers tax-free insurance coverage that can be used for various purposes, including outstanding debts or as a legacy for loved ones.
Drawbacks
- Limited coverage: Funeral insurance plans typically offer lower death benefit amounts than other types of life insurance.
- Potentially higher premiums: Premiums for final expense insurance can be higher than traditional life insurance for the same coverage amount.
- Waiting period: Some policies may have a waiting period before the full death benefit is available, typically within the policy’s first two or three years.
Types of final expense insurance
Understanding the various types of funeral insurance policies available can help you make an informed decision when selecting a policy. A funeral insurance policy may have different eligibility requirements and features compared to whole life or term life insurance, and is specifically designed to help cover funeral expenses. Some funeral insurance policies may expire or be canceled under certain conditions, so it’s important to review the terms carefully.
- Simplified-issue insurance: This policy involves answering fewer and simplified health questions but does not require a medical exam. Medical underwriting is streamlined, and coverage is typically approved more quickly than traditional life insurance policies. This option is ideal for those seeking fast coverage or those with pre-existing health conditions.
- Guaranteed-issue insurance: This type of policy does not require medical underwriting or health-related questions. Applicants are typically guaranteed acceptance, regardless of their chronic health or pre-existing medical conditions. The death benefit is usually limited during the initial years, and after the graded benefit period, the total coverage amount is payable. This policy benefits seniors or individuals with significant health concerns who may not qualify for other insurance options. Premiums tend to be expensive, and coverage amounts are more limited. Some insurers also allow temporary residents with valid work or study permits to apply for coverage, making these policies accessible to a wider range of applicants.
There are typically two main types of death benefits:
- Level death benefit: A level death benefit means the coverage amount remains constant throughout the policy’s life. If the insured person passes away, the beneficiaries will receive the total specified coverage amount stated in the policy. This type of death benefit provides a fixed payout, ensuring that the coverage amount does not change over time.
- Graded death benefit: A graded death benefit is a type of death benefit provision that comes into effect during the initial years of the policy, usually the first two or three years. During this period, if the insured person dies, the beneficiaries may receive a limited payout that is less than the total coverage amount. The specific payout amount is predetermined and stated in the policy. After the graded benefit period, the full death benefit becomes payable.
When considering final expense or funeral insurance, keep in mind that other personal factors, such as age, gender, and smoking status, can influence both your eligibility and the premiums you pay.
How does graded death benefit work?
If the policyholder passes away during this period, the death benefit payout may be limited or altered depending on the insured’s death circumstances.
- Natural causes: Some policies may provide a partial death benefit if the insured person passes away due to natural causes during the graded benefit period. The exact percentage of the payout can vary, such as 25%, 50%, or 75% of the coverage amount.
- Accidental death: In many cases, final expense insurance policies include a provision for full coverage in the event of accidental death during the graded benefit period. If the insured person dies of an accident, the total coverage amount specified in the policy will be paid to the beneficiaries.
- Suicide: Most final expense insurance policies have a suicide exclusion within the graded benefit period. If the insured dies by suicide during the first two years of the policy, the death benefit may not be paid out or may be limited to a return of premiums paid.
The graded benefit provision is designed to mitigate the risk for the insurance company, as they may have limited information about the policyholder’s health and may want to assess any potential pre-existing conditions. It allows the insurance company to protect against fraudulent claims or situations where the policyholder’s cause of death may be related to undisclosed health issues.
After the graded benefit period expires (typically two years), the policy usually transitions to a full death benefit payout, meaning that the policyholder’s beneficiaries will receive the entire coverage amount in the event of their death.
Real-life examples
Let’s say John purchases a final expense insurance policy with a coverage amount of $20,000. The policy has a graded benefit provision for the first two years.
Scenario 1: John passes away within the first year. Unfortunately, John unexpectedly passes away due to a heart-related condition during the first year of the policy. Since the policy is subject to the graded benefit provision, the insurance company may specify a partial death benefit payout during this period. In this case, let’s say the policy stipulates a 50% graded benefit for year one.
If the graded benefit is 50%, the insurance company will pay $10,000 to John’s beneficiaries instead of the $20,000 coverage. The remaining $10,000 would not be available as a death benefit.
Scenario 2: John passes away in the second year. In this scenario, John unfortunately passes away during the second year of the policy due to a non-accidental cause. The graded benefit provision still applies, but the terms may be different. Let’s assume the policy specifies a 75% graded benefit for year two.
With a 75% graded benefit, the insurance company will pay $15,000 as a death benefit to John’s beneficiaries, while the remaining $5,000 would not be available as part of the coverage amount.
Scenario 3: John passes away after the graded benefit period. The policy transitions to a total death benefit payout if John passes away after the two-year graded benefit period. In this case, the beneficiaries would receive the $20,000 coverage specified in the policy.
Final expense insurance vs. Term Vs. Permanent life insurance policy
The choice between the two depends on individual needs, financial goals, and the specific purpose of the coverage required. Final expenses insurance cost is generally lower than traditional life insurance because it offers smaller coverage amounts and uses simplified underwriting, making it a more affordable option for those seeking to cover end-of-life expenses.
Who needs final expense insurance?
Final expense insurance is generally suitable for individuals with specific concerns about covering the costs associated with their end-of-life expenses.
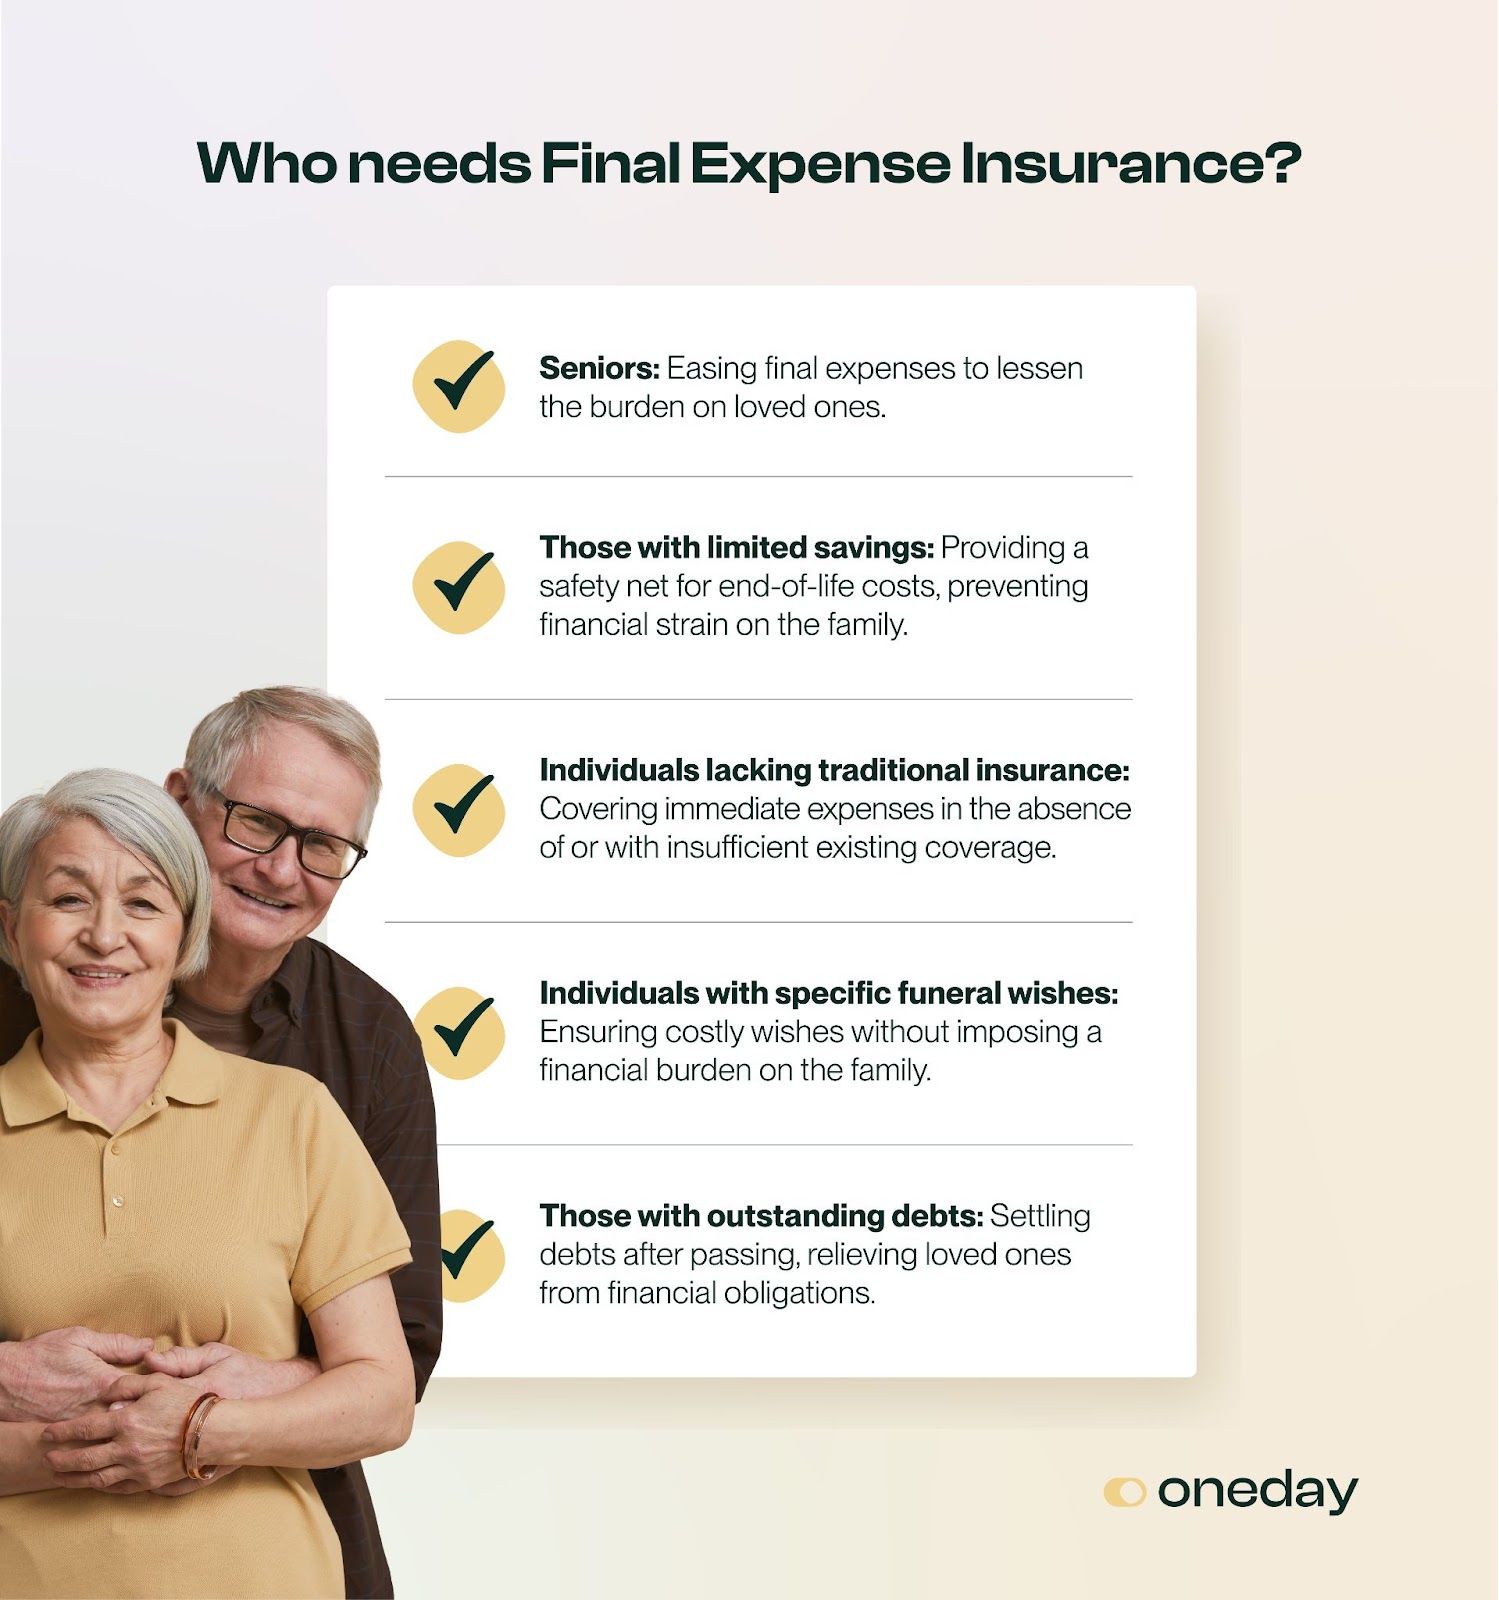
- Seniors or elderly individuals who want to ensure their loved ones are not burdened with the financial responsibilities of their final arrangements.
- Individuals with limited savings or who need a dedicated fund for end-of-life expenses.
- Those without traditional life insurance.
- Individuals with specific funeral wishes.
- Those with outstanding debts that they want to be settled upon their passing.
Does the government help you pay for a funeral?
In Canada, the Canada Pension Plan (CPP) does provide a one-time lump-sum death benefit to eligible contributors upon their death. This death benefit must be applied for and is intended to help with final expenses. However, it’s important to note that the amount provided by the CPP death benefit may not cover the total funeral cost.
The CPP death benefit is a one-time $2,500 payment (a top-up to $5,000 exists, but only where no CPP pension was ever paid and no survivor's pension is payable). The top-up applies to deaths on or after January 1, 2025. Not everyone qualifies: the person must have contributed to the CPP for at least one-third of the calendar years in their contributory period (and no fewer than three), or for at least 10 calendar years. The executor should apply within 60 days of the death. Our guide to the CPP death benefit covers who receives it, the survivor’s pension and how to apply.
While the CPP death benefit can provide some financial assistance to some people, it’s advisable to consider other options, such as personal savings, funeral insurance, or pre-planning, to ensure that final expenses are adequately covered. Having final expense insurance in place can help your family fulfill your final wishes, alleviate their burden, and provide peace of mind for you and your family.
How much does a funeral cost in Canada by province?
Costs vary widely by location and service type. A simple cremation might cost $2,000 to $3,000, while a traditional burial with service and headstone can reach $8,000 to $15,000 or more.
Provinces like Ontario and British Columbia generally fall on the higher end, while smaller provinces tend to be lower. Because costs fluctuate, it’s wise to contact local funeral homes for quotes before deciding how much coverage you’ll need.
| Province | Typical direct cremation (CAD) | Source (examples) |
|---|---|---|
|
British Columbia |
$1,900 – $2,200 |
Alternatives Funeral & Cremation Services (Metro Vancouver) “Simple Cremation” $1,999.65 incl. fees and taxes. |
|
Alberta |
$1,200 – $3,500 |
Basic Funerals Calgary “Direct Cremation” from $1,200. (Care Funeral Services) • Pierson’s Funeral Service (Calgary) “Direct Cremation” $3,495 (package). (Halifax Funerals) |
|
Saskatchewan |
$1,500 – $3,000 (typical range reported) |
Eirene (national cremation provider) overview of Saskatchewan cremation pricing and what’s included; cites local market ranges. |
|
Manitoba |
$2,900 – $4,200 |
Hemauer Funeral Home (The Pas) “Immediate Cremation” $4,170 (package). (IRP CDN) • (Winnipeg) Alterna Cremation article gives Canada and Prairie context and what’s typically included. (Martens Warman Funeral Home) |
|
Ontario |
$1,800 – $2,500 |
Simple Alternative Funeral Centres (Toronto) “Direct Cremation” package $1,895 (2023 GPL). (Harris Funeral Home) |
|
Québec |
$1,700 – $2,400 |
alaVida (Montréal) published line-item pricing (transport, cremation fee, container, docs, shelter, urn) that totals ≈ $1,800 before taxes for a basic, no-ceremony cremation. |
Policy expiration and renewal
Final expense insurance policies are typically designed to provide lifelong protection, but it’s important to understand how your specific policy works. If you have a whole life insurance policy, your coverage will remain in force for your entire lifetime as long as you continue to pay the premiums. This means your loved ones are guaranteed a payout to cover final expenses, regardless of when you pass away.
Some final expense insurance options may be structured as term life insurance, which provides coverage for a set period (such as 10, 20, or 30 years). These term policies may offer renewal options at the end of the term, but premiums could increase based on your age or health conditions at that time. Always review your policy’s terms and conditions to understand whether your coverage is permanent or if it will require renewal.
It’s also wise to periodically reassess your insurance needs, especially if your health conditions or financial situation change. Staying informed about your policy ensures that your final expense insurance continues to meet your needs and provides the intended support for your family.
How final expense insurance works in Canada – Conclusion
Final expense insurance offers accessible, lifelong coverage designed to remove financial stress from your loved ones at a difficult time. With no medical exams and guaranteed-acceptance options, it’s a practical solution for seniors and those with health challenges. Securing final expenses insurance can take the burden off your loved ones during a stressful time after your passing. Choosing the right coverage amount ensures your final wishes are carried out and costs are fully covered.
To explore final expense policies that fit your needs and budget, get a personalized quote with Oneday. Coverage for eligible applicants is subject to underwriting and provincial regulation.
Frequently asked questions about final expense insurance Canada
Can you pre-plan your funeral?
Yes, it is possible to plan for your funeral. Funeral pre-planning allows individuals to make arrangements and decisions regarding their funeral services, burial or cremation preferences, and other related details in advance.
What is the difference between life insurance and final expense insurance?
Life and final expense insurance are designed to provide financial security to your loved ones. However, life insurance typically provides a more considerable death benefit (millions of dollars) to cover various expenses, such as mortgage payments, education costs, and income replacement. Final expense insurance, on the other hand, is explicitly designed to cover funeral, burial, and other final arrangements, with a smaller death benefit (typically up to $50,000).
Does life insurance cover funeral expenses?
Life insurance can cover final expenses, depending on the policy and the death benefit amount. The beneficiaries can use the payout from a permanent life insurance policy to cover funeral costs and other expenses. However, if the death benefit is insufficient or already earmarked for different purposes, final expense insurance can be a valuable addition to ensure final expenses are covered.
How much does final expense insurance cost?
Final expense insurance costs vary depending on age, gender, health, and the coverage amount. Premiums tend to be more affordable than traditional life insurance policies, as the death benefit is typically smaller. A 60-year-old individual may have a monthly premium of $30 to $50 for a final expense policy with a coverage amount of $10,000 to $20,000. On the other hand, an 80-year-old individual may experience higher premiums, typically ranging from $100 to $200 per month, for a final expense policy with a coverage amount of $10,000 to $30,000.
What happens when you don’t have final expense insurance?
you don’t have final expense insurance, your family will cover the final and other end-of-life expenses.
Is final expense insurance legit in Canada?
Yes. It is ordinary life insurance, sold under provincial insurance law and sized to cover a funeral and final bills. The risk is the seller, not the product: an unlicensed agent, a company that is not a licensed insurer, or a pitch that hides a long waiting period. Check the licence with your provincial regulator, ask who underwrites the policy, and read what it pays in the first two years.
How do I check if a life insurance company is real?
Search your province's public licence register for the agent and the company (the links are in the section above), check that the insurer is on the Assuris list of member companies, and make sure your policy documents name that same insurer. If anything doesn't match, call the regulator before you pay.
How much is the CPP death benefit?
The CPP death benefit is a one-time $2,500 payment (a top-up to $5,000 exists, but only where no CPP pension was ever paid and no survivor's pension is payable). The top-up applies to deaths on or after January 1, 2025. The executor should apply within 60 days of the death (Government of Canada). Most funerals cost more than either amount.
Is there a waiting period on final expense insurance?
Often, yes. Guaranteed-acceptance policies and some simplified ones limit what they pay for a death from natural causes in the first two or three years, usually to a refund of premiums or part of the benefit. At Oneday, offers below our healthiest class carry a 24-month deferral: accidental death is paid in full from day one, a natural death in the window returns all premiums paid, and full coverage applies after 24 months. Healthier answers get full coverage from day one.
Can I cancel a final expense policy if I change my mind?
Yes. A new individual life policy comes with a free-look period, usually 10 days in Canada, to cancel for a refund (FCAC). Oneday's free look is 30 days. You can also stop a policy later, but premiums already paid are generally not returned once the free look has passed.
Where is Oneday available?
Oneday is available in seven provinces: Ontario, British Columbia, Alberta, Manitoba, Saskatchewan, New Brunswick and Nova Scotia.
Who underwrites my policy?
Oneday is a third-party administrator. Every policy is underwritten by Humania Assurance Inc., a Canadian life insurer founded in 1874 and a member of Assuris.
Sources:
- CRA, “Death benefits, Individuals”
- Government of Canada (CPP), “CPP Death Benefit”
- Financial Consumer Agency of Canada, “Getting an insurance policy”
- Canadian Life and Health Insurance Association, “G10: 10-day insurance contract rescission right”
- Assuris, “List of member companies”